Models of Collaboration
Support for growth strategies, transformations or M&A processes.
Our IT and subject-matter experts have in-depth specialist knowledge in their field.
We provide you with experienced interim managers who take on responsibility.
Customized expert teams for complex projects
We find the best experts for these companies
Private equity
Efficient support throughout the deal cycle
Corporates
Technical and management experts for operational excellence
Scale-ups
Strategic & operational support for growth
Scope

What Transaction Management Consulting Covers — and What It Does Not
Figures from a report are recalculated with a calculator before the purchase price negotiation

M&A consulting — depending on the firm also called transaction advisory, mergers and acquisitions consulting or M&A advisory — works on a matter that has a fixed date. It answers three questions, and in this order: what about the target company can be substantiated, which of that changes the price, and which of that somebody has to deliver after the signature. The first part is diligence work in the data room, the second is negotiation preparation with figures instead of postures, the third is integration work in day-to-day operations.

Between those parts sits a break that explains the whole discipline: the price is determined before signing, the value only arises after closing. Before signing, what counts is what can be read out of somebody else's documents within a few weeks. After closing, what counts is whether the assumptions used to justify that price actually materialize in the running business. The two halves call for different capabilities — and capacity is almost always bought only for the first. This is precisely where transactions fail whose diligence was faultless.

Where the boundaries run, in both directions: valuation itself, the financing structure and reporting to banks and investors are standing topics without a cut-off date and belong under corporate finance consulting. Legal representation, contract drafting and the statutory audit stay with the law firm and the auditor; M&A consulting supplies them with the facts they rely on. Put simply: corporate finance runs without a deadline, M&A is the transaction itself — and it has a date.

What M&A consulting does not deliver. It does not produce a buyer or a seller on request, it does not replace the entrepreneurial decision on whether to proceed, and it cannot make a diligence exercise better than the data room it is given. Where documents are missing, the result is a named gap with a proposal for covering it — not a number. And it gives no assurance on synergies that nobody in the house will own after closing.

Triggers

When a Transaction Needs Dedicated Management Capacity

Not every deal needs a dedicated transaction manager. A company with a practiced corporate development team, an established PMO and free capacity in finance, legal and IT runs smaller transactions on its own. In the situations below the calculation changes, and for a structural reason: most companies do not run transactions often enough to keep that capacity in-house, and the people who know the business are needed to run it while the deal is underway.

1. Signing Is Set, the Workstreams Are Not Coordinated

  • Legal, tax, finance and HR each work with their own advisor and their own list of open items.
  • Nobody holds the dependencies and the date everything is counted back from.
  • A transaction PMO turns parallel activity into one plan with owners and deadlines.

2. Conditions Precedent Stand Between Signing and Closing

  • Merger control clearance, financing, consents from contract partners and employee representation run on different clocks.
  • Each condition has an owner on one side and a dependency on the other.
  • Without central tracking the closing date slips — and with it the purchase price mechanics.

3. A Carve-out Needs a Separation Plan

  • What is sold has to be separated from what stays: people, contracts, systems, shared services.
  • Every gap becomes a transitional service the seller has to provide after closing.
  • The separation plan decides whether the business is operational on Day 1.

4. Transitional Services Have to Be Defined and Run

  • Transitional service agreements need a scope, service levels, prices and an exit date before signing.
  • After closing they have to be steered, billed and wound down on schedule.
  • Without an owner, temporary services turn into permanent costs.

5. Day 1 Readiness Is Not Secured

  • On the first day after closing, bank accounts, payroll, IT access, contracts and customer communication have to work.
  • Each item is small; together they decide whether the business runs without interruption.
  • A Day 1 checklist with named owners is the shortest way there.

6. The Deal Team Is Back in the Day Job

  • After closing, the people who negotiated the deal return to their regular roles.
  • Integration and the first 100 days need continuous steering, not occasional attention.
  • External capacity bridges the period until the organization takes over on its own.

Do you recognize one of these situations? Twenty minutes is enough for a first assessment: which workstream needs steering first, what can realistically be achieved by your closing date — and whether external capacity is required for it.

Disciplines

Workstreams: From Signing to Closing and Day 1

Transaction management workstreams can be staffed singly or in combination, and they follow the sequence of a deal: the PMO sets up the structure, signing-to-closing management secures the path to completion, separation and TSA management carry the carve-out, and Day 1 readiness and integration management carry the business across the threshold. Most engagements start with the PMO and grow into the neighboring workstreams, because they depend on each other: a transitional service agreement without a separation plan has no scope, and a Day 1 plan without closing tracking has no date.

Transaction PMO and Deal Governance

Setting up and running the transaction office: one master plan counted back from signing and closing, workstreams with named owners, a log of open items, risks and decisions, and a reporting rhythm for the steering committee. The PMO coordinates internal teams and external advisors — law firms, tax advisors, auditors, banks — so that questions are answered once and decisions are taken on time.

Signing-to-Closing Management

Tracking everything that has to happen between signing and closing: conditions precedent such as merger control clearance, financing and third-party consents, the closing checklist, the funds flow and the documents required on the closing date. The result is a closing that takes place on the agreed date — and a record of which obligations continue after it.

Due Diligence Coordination and Data Room

Organizing the diligence process rather than performing every review: data room structure, question and answer lists, management sessions and deadlines across the finance, commercial, legal, tax and IT workstreams. On the sell side this keeps the organization able to answer; on the buy side it makes sure the findings reach the people who negotiate the contract.

Separation and Carve-out Management

Separating a business from a larger group: defining the perimeter of what is sold, allocating people, contracts, assets and licenses, separating shared IT systems and data, and building the stand-alone functions the business needs after closing. The separation plan is the basis for both the transitional services and the Day 1 plan.

Transitional Service Agreement (TSA) Management

Defining, pricing and running transitional service agreements: which services the seller continues to provide after closing, at what service level, at what price and for how long. After closing, TSA management steers delivery and billing and drives the exit from each service on schedule, so that temporary arrangements do not turn into permanent costs.

Day 1 Readiness and Integration Management

Preparing the first day after closing and the period after it: legal entity and banking set-up, payroll, IT access, contract transfers, customer and employee communication, and an integration plan for the first 100 days. Integration management then tracks the measures behind the deal rationale until the organization takes them over.

Which workstream needs steering first can be framed in a short conversation — including the honest answer on whether bringing in external capacity pays for itself.

Engagement Models

How Transaction Management Capacity Is Brought In

In a transaction, the need for steering capacity changes with the phase: before signing the focus is on the process, between signing and closing on the conditions, after closing on separation and integration. Four ways of bringing people in have proven themselves. They can be combined and often change along the way. The same frame applies to all of them: named internal ownership, a scope fixed before the start, and confidentiality that both sides accept.

Transaction Lead

One Person Who Runs the Deal Process

One experienced transaction manager takes over the process on behalf of the company: master plan, advisor coordination, steering committee preparation and the closing checklist. The usual form when nobody in the house has run a transaction of this kind before, or when the corporate development team is already committed.

Transaction PMO

A PMO Team Across Several Workstreams

Two to five external specialists staff the transaction office and the critical workstreams — for example finance, separation and IT — under internal leadership. The usual form in larger transactions and carve-outs, where the number of dependencies exceeds what one person can track.

Separation and TSA

A Dedicated Carve-out or TSA Mandate

A specialist with a narrowly framed mandate: build the separation plan, define and price the transitional services, or run an existing portfolio of transitional service agreements to its exit. The result is a defined scope with dates and owners, without a larger structure around it.

Day 1 and Integration

Steering the First 100 Days

A small unit that prepares Day 1 and steers the integration measures afterwards: progress, dependencies and risks come together there, with a reporting line that triggers decisions instead of producing status slides. It ends at a handover point that is fixed at the start.

Industry Rhythm

Transaction Management by Industry: Where Execution Gets Difficult

The mechanics of a transaction are similar across industries; the points at which execution gets difficult are not. In machinery and plant engineering, running projects and their guarantees have to be transferred without interrupting delivery. In retail and consumer goods, supply chain, purchasing terms and store or warehouse operations must work on Day 1. In software, the separation of shared platforms, licenses and customer data decides the timeline.

In healthcare and pharma, permits and approvals are tied to legal entities and sites and have to be transferred or newly applied for. In energy, grid connections, offtake agreements and regulatory notifications shape the closing conditions. In real estate and construction, financing covenants, leases and project guarantees set the pace. We therefore staff by transaction and industry experience: somebody who has executed comparable deals knows which item on the closing checklist will take longest. The focus areas below are a selection; neighboring industries we staff from the same pool of experience.
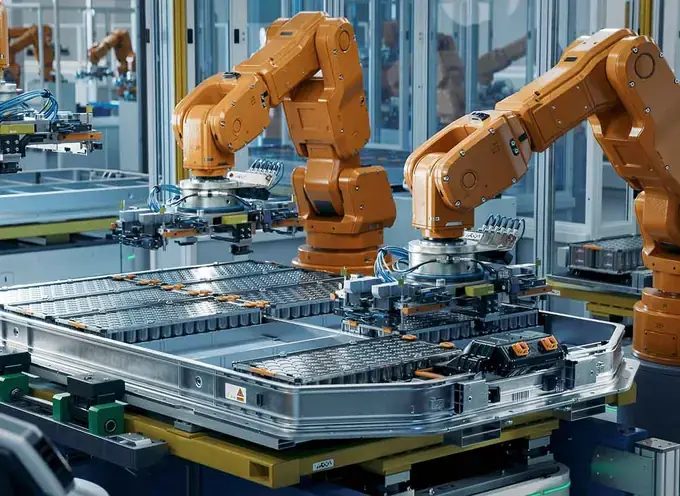
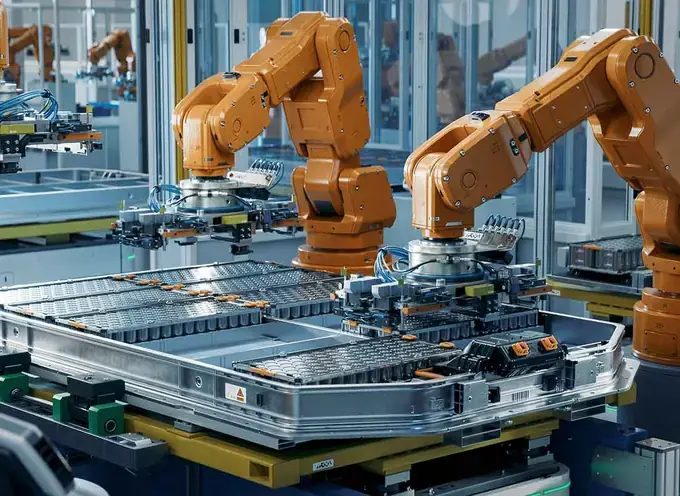
Robotic arms on an assembly line in machinery and plant engineering

Machinery & Plant Engineering

Shoppers moving through a supermarket, standing for retail and consumer goods

Retail & Consumer Goods

A person in front of key figures and growth curves of a technology business

Software & Technology

A hand with a heart symbol and health icons, standing for healthcare and pharma

Healthcare & Pharma

Wind turbines with an overlaid price curve, standing for energy and utilities

Energy & Utilities

High-rise buildings seen from below, standing for real estate and construction

Real Estate & Construction

Transaction Types

Transaction Types and Where Execution Breaks Down

Most transaction management mandates fall into four types. Each has a typical starting position, an execution focus and a point at which it tips — the place where, in experience, time or value is lost if nobody owns it.

Company Sale and Succession

Starting position: the sale is decided, the organization has never run a transaction, and the owner is needed in the business at the same time. The execution focus is the sell-side process: documents, data room, buyer questions and the path to signing. The tipping point: answering capacity. If questions from the buyer side pile up unanswered, the timeline and the negotiating position suffer together.

Acquisition and Add-on

Starting position: the purchase agreement is in negotiation, the target has to be brought into an existing group, and the deal team is small. The execution focus is the path from signing to closing and Day 1. The tipping point: the conditions precedent. Merger control, financing and third-party consents run on different clocks, and one missing consent moves the closing date.

Carve-out from a Group

Starting position: a division is to be sold but shares people, contracts, systems and services with the rest of the group. The execution focus is the separation plan and the transitional services. The tipping point: the scope of the transitional service agreement. Whatever is not defined before signing has to be provided after closing anyway — usually on worse terms.

Integration After Closing

Starting position: the deal has closed, the deal team is back in the day job, and both organizations carry on unchanged. The execution focus is Day 1 and the first 100 days. The tipping point: the first weeks. Management structure, reporting and decision paths are settled in that period — after it they are only confirmed.

Roles We Staff

Profiles We Staff in Transactions
Which profile a transaction needs depends on its phase and type: running the deal process calls for different experience than separating shared IT systems or steering transitional services. The profiles below come from the M&A & Due Diligence and Finance & Controlling practices; this is a selection, and further roles are reachable through the category pages. Task profile, typical assignments and the daily rate range are published openly on each role page.

From Kick-off to Handover: The Stages of Transaction Management

Scope and duration depend on the size of the deal, the number of workstreams and the starting point; the sequence does not: first set up the structure, then run the process to signing, then secure the path to closing, then separate, then prepare Day 1, then hand over. We skip no stage and shorten one only where the organization already has solid structures in place.
Stage 1: the transaction office, timeline and governance are set up

1. Set Up the Transaction Office

A timeline counted back from the target dates for signing and closing, with workstreams, owners and a steering committee rhythm.
Confidentiality, the circle of people in the know and the coordination of external advisors are fixed before work starts.
The result is one master plan that all internal teams and advisors work against.
Stage 2: the process up to signing is coordinated across all workstreams

2. Run the Process to Signing

Data room, question lists and management sessions are organized so that the organization can answer without stopping the day job.
Findings from the diligence workstreams are routed to the people negotiating the contract.
The result is a signing prepared for the agreed date, with the open points known.
Stage 3: conditions precedent and the closing checklist are tracked to completion

3. Secure the Path to Closing

Conditions precedent, consents and approvals are tracked with owners and dates on both sides.
Closing checklist, funds flow and closing documents are prepared well before the closing date.
The result is a closing that takes place as planned, and a list of the obligations that continue after it.
Stage 4: the separation plan and transitional services are defined

4. Separate and Define Transitional Services
In carve-outs, the perimeter of the business is defined and people, contracts and systems are allocated.
Transitional services get a scope, service levels, prices and an exit date before signing.
The decision on what to accept stays in the house; external support prepares, calculates and documents.
Stage 5: Day 1 readiness and the integration plan are prepared before closing

5. Prepare Day 1 and the First 100 Days
The Day 1 checklist covers legal entities, banking, payroll, IT access, contracts and communication.
On the first day after closing, contacts, reporting lines and decision paths are known on both sides.
Integration measures get an owner and a date; duplicate structures get an end date.
Stage 6: transitional services end and responsibility is handed over

6. Exit Transitional Services and Hand Over

Transitional services are wound down on schedule, with stand-alone functions in place before each service ends.
Progress is measured against the assumptions behind the deal rationale, not against a new plan.
The handover point is fixed at the outset: after it your organization runs the business on its own.
Daily Rates

What Transaction Management Consulting Costs — Daily Rates and Budget Frames

We bill transaction management by daily rate, not as a success fee on transaction volume. The rate follows from five factors: seniority and the number of completed transactions; the type of deal (carve-outs and cross-border transactions sit above the average); depth of responsibility — running a single workstream sits below leading the whole transaction office; the share of on-site presence; and availability in the profile sought under time pressure.

For the transaction roles shown below, the ranges in our pool currently sit between €1,200 and €2,000 per day. They are published openly for each role — on the relevant role page, not on request:

All ranges come from the role pages and are kept up to date there.

How to budget transaction management. You plan in person-days per phase, not as a percentage of the purchase price. The phase up to signing is driven by the number of workstreams and advisors; the phase between signing and closing by the number and complexity of the closing conditions; separation and transitional services by the number of shared functions and systems. Integration is staffed for a duration, not for a scope.

Two points that are worth more than a discount before you commission anything. First: plan the capacity for the period after signing at the same time as the capacity before it — that is where deals most often run short. Second: the most expensive item in a transaction is rarely the fee, it is capacity left unstaffed after closing. We say before the engagement starts if we think a task can be solved in-house.

These are ranges, not fixed prices. What your project actually costs depends on the scope — and we settle that beforehand, not in the invoice.

Which experience a transaction needs depends on its phase: running a deal process calls for different skills than separating shared systems. Relevant profiles sit under M&A & Due Diligence — among them Freelance M&A Consultant, Interim Carve-out Manager, Freelance Due Diligence Consultant, Freelance Cross-Border M&A Advisor and Freelance Post-Merger Integration Consultant. Alongside these we staff from Finance & Controlling, including the Interim CFO, and from Transformation & Change Management. The strategic side of a deal — due diligence, valuation and purchase price — is covered under M&A consulting, the financing side under corporate finance consulting.

Market Figures

The Succession Wave in the Mittelstand Makes Selling a Company the Normal Case

109,000

medium-sized companies a year are aiming to settle succession through to the end of 2029, according to KfW — most of them for the first and only time.
KfW Research, Nachfolge-Monitoring Mittelstand 2025

42%

of Mittelstand owners planning succession are considering a sale to an external buyer instead of a handover within the family.
KfW Research, Fokus Volkswirtschaft No. 526

+34%

higher than in 2019 are the purchase prices sought in the Mittelstand — which widens the expectation gap between the two sides rather than closing it.
KfW Research, Nachfolge-Monitoring Mittelstand 2025
Questions and Answers

Frequently Asked Questions About Transaction Management Consulting

Transaction management consulting — also called deal execution or transaction management — covers the execution of a purchase, sale, merger or carve-out once the strategic decision has been made: setting up and running the transaction PMO, coordinating internal teams and external advisors, tracking conditions precedent between signing and closing, managing separation and transitional service agreements, and preparing Day 1 and the integration. Anyone searching for transaction management consultants or transaction advisors for deal execution usually means this service.
M&A advisory works on the deal itself: finding and assessing targets, due diligence, valuation, purchase price and contract terms. Transaction management works on the execution: the plan, the workstreams, the dependencies and the path from signing to closing and Day 1. Many transactions need both; the strategic side is covered under M&A consulting, and the two can be staffed together or separately.
After signing, the focus shifts from negotiation to completion. The transaction manager tracks the conditions precedent — such as merger control clearance, financing and third-party consents — prepares the closing checklist and the funds flow, coordinates the closing documents with law firms and banks, and makes sure that everything needed for Day 1 is in place. After closing, the role usually continues into the management of transitional services and the first 100 days of integration.
Yes. Carve-outs are one of the most frequent reasons to bring in transaction management capacity. The work covers defining the perimeter of the business being sold, allocating people, contracts and systems, building stand-alone functions, and defining and running the transitional service agreements that bridge the period after closing. For this we staff interim carve-out managers and separation specialists from our network.
A transitional service agreement governs the services a seller continues to provide to the sold business for a limited period after closing — typically IT, finance, HR, purchasing or logistics. It defines scope, service levels, prices and an end date for each service. TSAs are negotiated before signing and have to be actively managed after closing, so that each service is replaced by a stand-alone solution before it expires.
We bill by daily rate, not as a commission on transaction volume. For the transaction roles we staff, the published ranges currently sit between €1,200 and €2,000 per day, depending on seniority, type of deal, depth of responsibility and availability under time pressure; each role publishes its own range on its own page. You plan a project in person-days per phase — before signing, between signing and closing, and after closing.
Matching profiles from our network of around 23,000 Freelance Management Consultants, Interim Managers and IT and Subject-Matter Experts are typically available within 24–36 hours. The actual start depends on the availability of the profile and on confidentiality arrangements, which in transactions are usually settled before any documents are shared.
It is worth it when a transaction has more workstreams than the internal team can coordinate; when conditions precedent and consents have to be tracked across several parties; when a carve-out needs a separation plan and transitional services; when Day 1 readiness has no owner; or when the deal team has to return to the day job right after closing. It is not worth it when a practiced corporate development team and an established PMO are in the house and have free capacity for both phases — before and after the signature.
You can rely on us

Excellent. We are not the only ones who think so.

consultingheads has received several awards from leading trade magazines and independent third parties.
F.A.Z.-Institut seal TOP Berater 2026
kununu seal Top Company 2025
brand eins seal Beste Berater 2025
kununu seal Top Company 2024
brand eins seal Beste Berater 2024
kununu seal Top Company 2023
brand eins seal Beste Berater 2019
brand eins seal Beste Berater 2021
brand eins seal Beste Berater 2020
brand eins seal Beste Berater 2026
consultingheads Logo
brand eins seal Beste Berater 2026
Contact

Let's talk about your closing date.

Your transaction timeline framed in twenty minutes
One named first workstream instead of a methodology overview
Open daily rate ranges before you send an enquiry
Twenty minutes in which we frame your starting position and name which workstream needs steering first — and whether the task is in the right place with us.